120 posts found for people with disabilities
More than 150 organizations call for a new approach to defining disability in Canada
Disability Alliance BC has joined more than 150 organizations from across Canada calling on the federal government to establish a single, rights-based definition of disability and to change how people with disabilities qualify for federal supports.
The joint statement, released ahead of the upcoming federal budget, sets out two complementary paths:
- A new rights-based system for defining disability, built outside the tax system.
- Immediate fixes to the Disability Tax Credit (DTC).
Download the joint statement.
Why this matters
The DTC is a gateway to the Canada Disability Benefit and 16 other federal disability programs, plus a growing number of provincial and territorial programs. It was created nearly 40 years ago as a tax-relief measure and was never designed to be the eligibility test for all other disability supports.
Far too few eligible people access the DTC because of persistent administrative barriers. Statistics Canada reports that fewer than one in six people with disabilities in Canada, and only about a third of people with very severe disabilities, access the DTC. This means hundreds of thousands of people with disabilities aren’t receiving the benefits they’re entitled to.
People with disabilities in Canada are also 50 per cent more likely to experience poverty than people without disabilities and twice as likely to experience food insecurity. Failing to bridge these gaps means failing to uphold Canada’s responsibility to protect the fundamental human rights of people with disabilities.
A question of principle
Adopting the proposed changes is a question of principle. No one should be kept from disability supports by an overly restrictive definition of disability or by persistent administrative barriers that make applying for benefits too difficult.
Getting this right would also make government work better. Federal programs — including the DTC, the Canada Pension Plan disability benefit, and veterans programs — use different definitions of disability and different eligibility rules, which can mean repeated assessments. A single definition and a centralized process for establishing disability status would cut that duplication for people with disabilities, medical practitioners, and the government.
What the statement calls for
The statement’s signatories recognize progress has been made toward reforming the DTC.
Recent federal administrative changes announced as part of this year’s Spring Economic Update are expected to unlock an estimated $345 million in support over six years for people facing access barriers. Lasting change will require fundamental reform.
The statement calls on the federal government to commit to a collaborative process to design a new eligibility system that would:
- Use the Accessible Canada Act’s definition of disability as the starting point for access to federal disability programs.
- Create a centralized process for determining disability status outside the tax system that’s dignified, accessible, and rights-based.
- Automatically extend federal disability certification to people already receiving disability benefits through provincial or territorial social assistance programs.
It also calls for immediate action to remove barriers in the current DTC application process while the new system is built, including:
- A new plain-language application form.
- Direct reimbursement of medical practitioners who certify applications.
- Fewer unnecessary temporary certificates and simpler renewals.
- An option for supported decision-making.
- More funding for the Disability Benefit Navigation program.
All reforms must be designed in partnership with people with disabilities, in keeping with Canada’s human rights commitments under the United Nations Convention on the Rights of Persons with Disabilities, including the principle of “nothing about us without us.”
Together, we can build a Canada where no eligible person is kept from disability supports by administrative barriers.
Read the full statement and the list of signatories: Download the joint statement.
The SDSP: A lesser known RDSP option for Shortened Life Expectancy
The RDSP was designed as a long-term financial tool for people with the Disability Tax Credit, but life doesn’t always follow a long-term plan. The Registered Disability Savings Plan is often associated with long term savings, government grants and bonds, and planning for the future. However, for an RDSP beneficiary with a shortened life expectancy of five years or less, there is an important option that many families don’t know about: the Specified Disability Savings Plan (SDSP).
An SDSP is a special designation that can provide greater flexibility in accessing money already saved in an RDSP. It can be important when the purpose of financial planning shifts from long term savings to making resources available during the beneficiary’s lifetime.
To qualify for an SDSP, a licensed doctor or a nurse practitioner can certify in writing that a person with a disability is unlikely to survive more than five years. The RDSP holder then makes the SDSP selection with the financial institution that is administering the plan for them. The person with the RDSP can either keep the RDSP under the normal specified year rules, or they can elect to turn their RDSP into an SDSP.
Specified year RDSP vs. SDSP:
An RDSP does not automatically become an SDSP without the beneficiary’s permission. When a shortened life expectancy is certified by the doctor or nurse practitioner, the RDSP can remain in an RDSP during a specified year, or the holder can choose to have it turn into an SDSP. Understanding the difference between these options is an important part of making an informed decision.
A specified year RDSP can provide significant withdrawal flexibility, while the SDSP provides its own set of rules intended to allow greater access to the plan without the usual proportional repayment of the assistance holdback amount.
Under the regular RDSP rules, early withdrawals can trigger a proportional repayment of grants and bonds that were paid into the plan in the preceding 10 years. Generally, for every $1 withdrawn, $3 of grants and bonds can become subject to repayment up to the applicable assistance holdback amount.
The SDSP provides an important exception; an SDSP is important because early withdrawals don’t trigger the repayment assistance holdback amount (i.e. grants and bonds that are subject to the 10-year repayment rules) within the SDSP limits.
Generally, the SDSP permits up to $10,000 of taxable RDSP withdrawals per year without triggering the repayment of the assistance holdback amount. There are circumstances where the Lifetime Disability Assistance Payment (LDAP) formula requires a larger amount to be paid, in which case the $10,000 limit does not apply in the same way.
Things to Consider about the SDSP:
Once you elect to turn your RDSP into an SDSP, no further contributions can be made to this plan. This plan can also not receive new Canada Disability Saving Grants or Disability Savings Bonds. The beneficiary cannot accumulate new grant or bond carry forward amounts under the SDSP and payments from the plan must begin within the applicable time frame.
For example, a family may have an RDSP with significant government contributions and a history of making regular contributions. If the beneficiary develops a condition associated with a shorter life expectancy, the family may need to consider whether maintaining the RDSP’s ability to receive future contributions and incentives is more important than having the additional withdrawal flexibility provided by the SDSP.
Before making an SDSP election, it can be worthwhile to speak with the RDSP issuer and a financial planner, tax professional, or other qualified advisor who understands the RDSP rules.
Upcoming Webinar: MSDPR Reconsiderations and Appeals
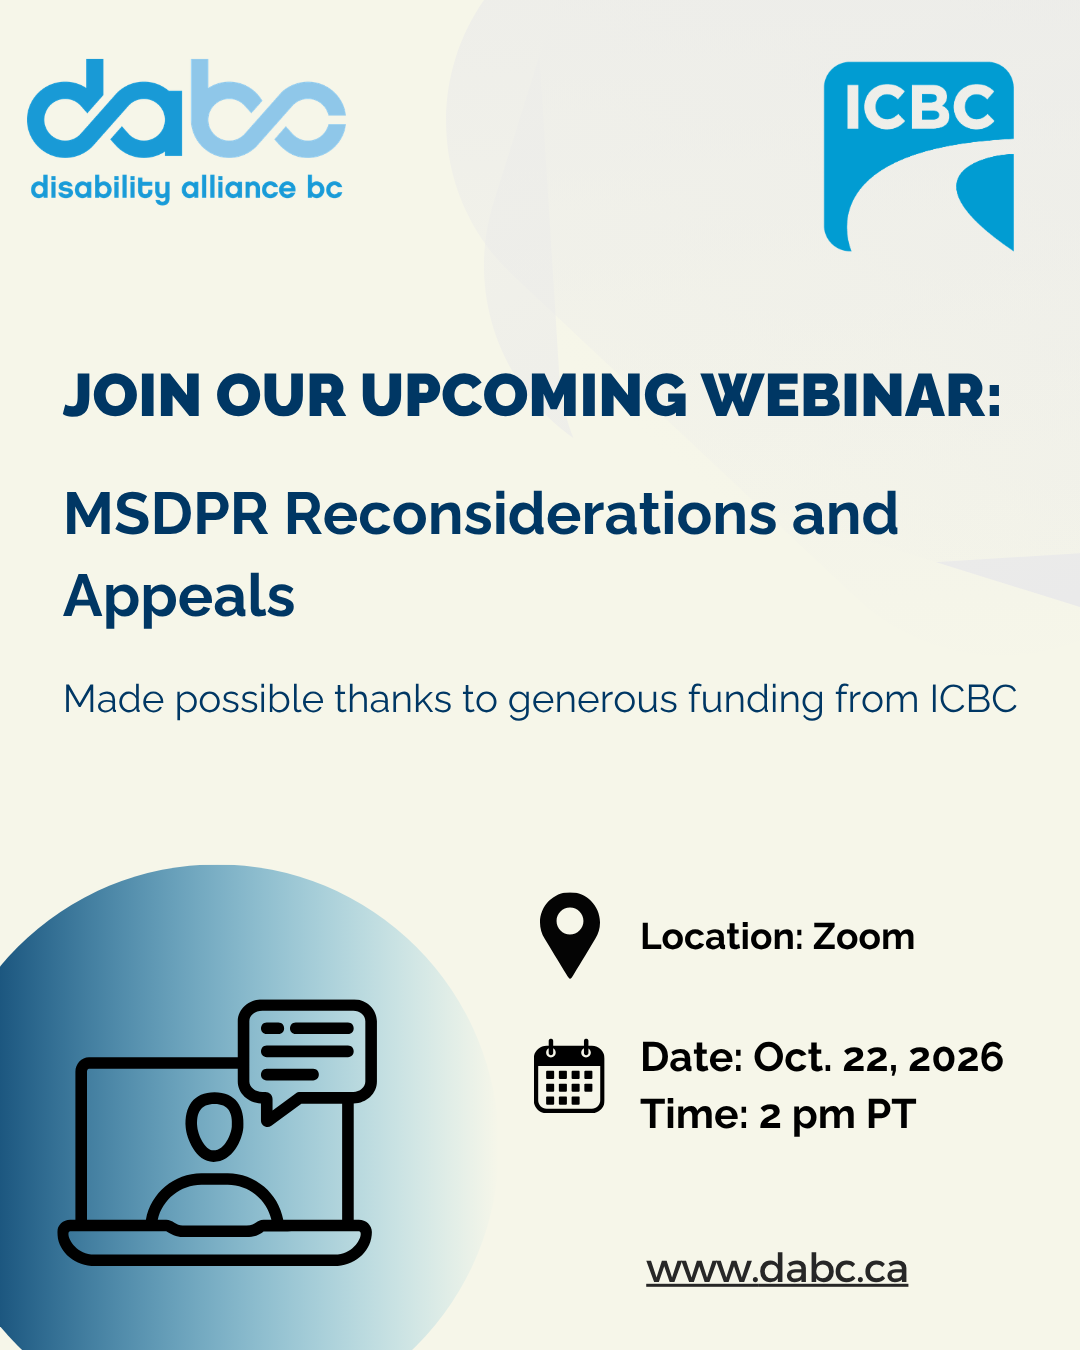
Join our upcoming webinar on October 22nd – a general overview of the process and tools for reconsiderations and hearings with the Ministry of Social Development and Poverty Reduction.
When: Thurs, October 22nd, 2026 at 2 pm PT
Where: Zoom
Register here: Registration link
Webinar made possible thanks to generous funding from ICBC.