The RDSP was designed as a long-term financial tool for people with the Disability Tax Credit, but life doesn’t always follow a long-term plan. The Registered Disability Savings Plan is often associated with long term savings, government grants and bonds, and planning for the future. However, for an RDSP beneficiary with a shortened life expectancy of five years or less, there is an important option that many families don’t know about: the Specified Disability Savings Plan (SDSP).
An SDSP is a special designation that can provide greater flexibility in accessing money already saved in an RDSP. It can be important when the purpose of financial planning shifts from long term savings to making resources available during the beneficiary’s lifetime.
To qualify for an SDSP, a licensed doctor or a nurse practitioner can certify in writing that a person with a disability is unlikely to survive more than five years. The RDSP holder then makes the SDSP selection with the financial institution that is administering the plan for them. The person with the RDSP can either keep the RDSP under the normal specified year rules, or they can elect to turn their RDSP into an SDSP.
Specified year RDSP vs. SDSP:
An RDSP does not automatically become an SDSP without the beneficiary’s permission. When a shortened life expectancy is certified by the doctor or nurse practitioner, the RDSP can remain in an RDSP during a specified year, or the holder can choose to have it turn into an SDSP. Understanding the difference between these options is an important part of making an informed decision.
A specified year RDSP can provide significant withdrawal flexibility, while the SDSP provides its own set of rules intended to allow greater access to the plan without the usual proportional repayment of the assistance holdback amount.
Under the regular RDSP rules, early withdrawals can trigger a proportional repayment of grants and bonds that were paid into the plan in the preceding 10 years. Generally, for every $1 withdrawn, $3 of grants and bonds can become subject to repayment up to the applicable assistance holdback amount.
The SDSP provides an important exception; an SDSP is important because early withdrawals don’t trigger the repayment assistance holdback amount (i.e. grants and bonds that are subject to the 10-year repayment rules) within the SDSP limits.
Generally, the SDSP permits up to $10,000 of taxable RDSP withdrawals per year without triggering the repayment of the assistance holdback amount. There are circumstances where the Lifetime Disability Assistance Payment (LDAP) formula requires a larger amount to be paid, in which case the $10,000 limit does not apply in the same way.
Things to Consider about the SDSP:
Once you elect to turn your RDSP into an SDSP, no further contributions can be made to this plan. This plan can also not receive new Canada Disability Saving Grants or Disability Savings Bonds. The beneficiary cannot accumulate new grant or bond carry forward amounts under the SDSP and payments from the plan must begin within the applicable time frame.
For example, a family may have an RDSP with significant government contributions and a history of making regular contributions. If the beneficiary develops a condition associated with a shorter life expectancy, the family may need to consider whether maintaining the RDSP’s ability to receive future contributions and incentives is more important than having the additional withdrawal flexibility provided by the SDSP.
Before making an SDSP election, it can be worthwhile to speak with the RDSP issuer and a financial planner, tax professional, or other qualified advisor who understands the RDSP rules.
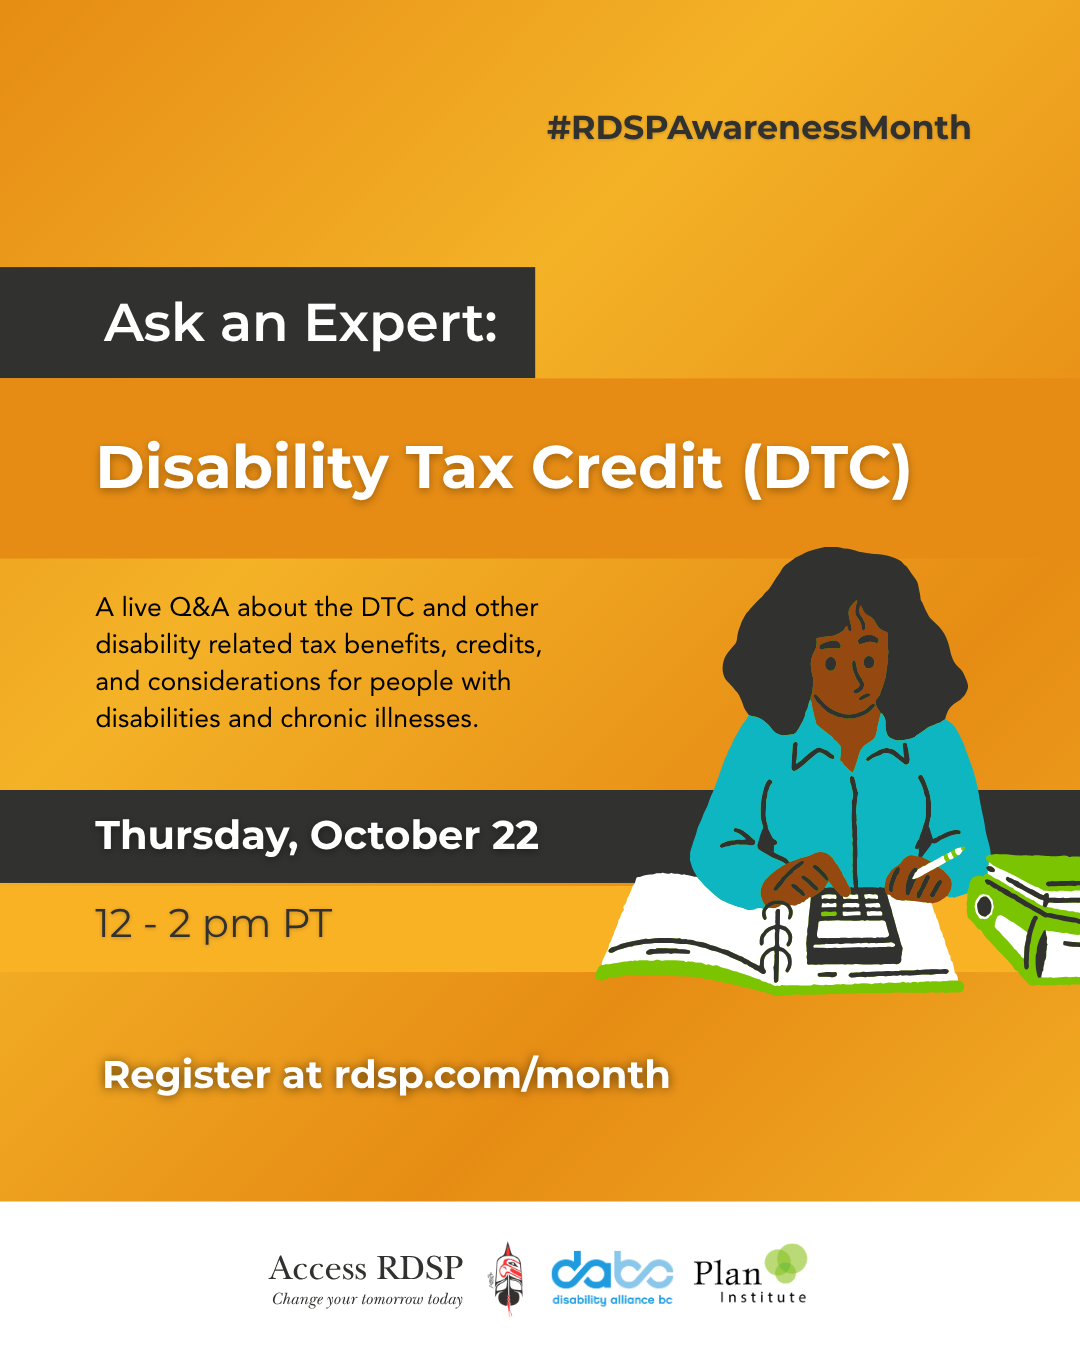
Ask our experts your questions about the Disability Tax Credit (DTC)!
Getting DTC approval is a big step toward starting your Registered Disability Savings Plan (RDSP). Join us on October 22 for a live Q&A (webinar) about the DTC and the benefits you can access with approval.
This #RDSPAwarenessMonth, don’t miss the chance to learn what you may be eligible for.
One of the biggest challenges with accessing the Disability Tax Credit is the application process. Luckily, changes are coming into effect that will make the application process easier. The DTC is based on the effects of disability or impairment, not simply having a particular diagnosis. Applicants have traditionally needed a qualified medical practitioner to provide detailed information about how their impairment affects specific activities of daily living and whether the impairments meet the legislated requirements for the DTC.
The process can be time consuming for applicants and medical practitioners. However, things are being made simpler. As part of the federal government’s 2026 Spring Economic update which announced changes to the DTC, the application process is being streamlined for people with certain long-lasting medical conditions as of 2027. At the same time, beginning with DTC certificates issues after 2026, more types of health professionals will be able to certify certain impairments. These changes will make the DTC easier to access for many Canadians.
Under the new streamlined approach, if an individual has one or more of the medical conditions on the designated list, a qualified medical practitioner will generally only need to certify that the individual has the condition. This means the practitioner will no longer have to complete the same detailed assessment of how the condition affects the person’s daily living activities. However, the CRA still retains the authority to request additional medical information when necessary, and the underlying legislative requirements for the DTC are unchanged.
What this means is that instead of asking a medical practitioner to document the functional consequences for a condition that the CRA has identified, the new process puts greater emphasis on the diagnosis itself for these specific conditions.
Conditions included are:
Alzheimer’s disease
Amyotrophic lateral sclerosis (ALS)
Angleman syndrome
Autism spectrum disorder, level 3
Bilateral blindness
Severe or profound bilateral hearing loss
Severe Cerebral Palsy
Stage III or higher COPD
Cystic Fibrosis
Dementia
Down Syndrome
Advanced or severe Duchenne Muscular Dystrophy
Huntington Disease
Permanent colostomy or ileostomy
Severe Intellectual disability
Paraplegia
Advanced or severe Parkinson’s disease
Quadriplegia or Tetraplegia
Renal failure requiring lifelong dialysis
Lifelong continuous supplemental oxygen
Severe schizophrenia
Severe Sickle cell disease requiring transfusions
Spinal muscular atrophy types I and II
Severe stroke with no functional recovery
Severe traumatic brain injury
Certain upper and lower limb amputations
And a number of other specified conditions that can be found here.
Another important change is beginning in 2027; the list of health professionals who can certify certain types of impairments will expand.
For example, podiatrists will be able to certify impairments affecting walking within their scope of practice. Physiotherapists will be able to certify impairments affecting feeding and dressing, in addition to walking and certain cumulative effect assessments. Speech language pathologists will be able to certify certain impairments affecting feeding in addition to speaking, and certain cumulative effects assessments. Occupational therapists will be able to certify impairments affecting eliminating bodily waste, in addition to their existing areas. This means that instead of having to find another practitioner, many people wil be able to work with a practitioner who already understands their condition and functional limitations.
Overall, the changes coming into effect in 2027 may make it easier for many people to navigate the DTC, and understanding these changes is important. If you have a condition included in the streamlined list, talk to your medical practitioner about the new certification requirements. If you have been told in the past that applying for the DTC would be too complicated, it may be worth revisiting the question, considering the new rules. Don’t assume you aren’t eligible; the DTC may be more available to you than you think.
Error validating access token: The session has been invalidated because the user changed their password or Facebook has changed the session for security reasons.